Today's Opinions, Tomorrow's Reality
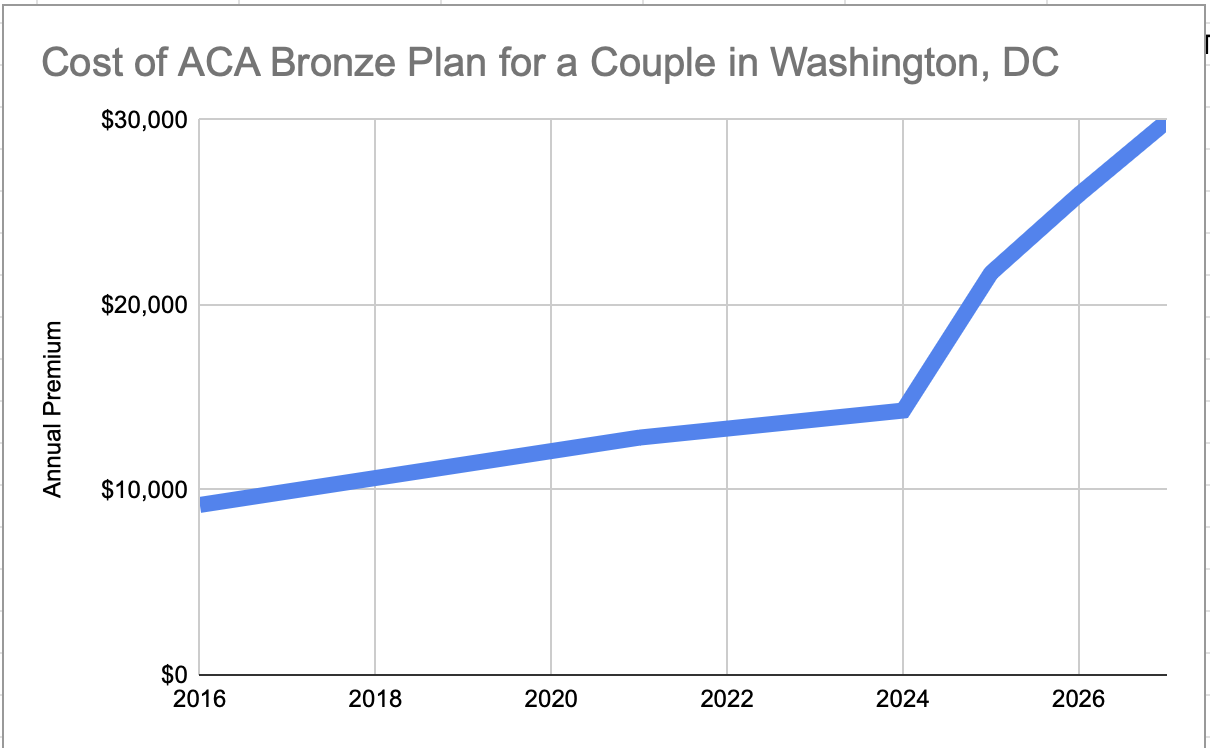
The Unaffordable Affordable Care Act By David G. Young Washington, DC, October 27, 2026 -- Republicans failed to repeal Obamacare. Democrats might succeed in destroying it for them. When the Affordable Care Act was passed back in 2010, it promised a new era of freedom for Americans. Until that day, Americans had been shackled to their employers to get health insurance. America's bizarro health system was born from World War II labor shortages -- employers offered free health care to circumvent the government's wartime wage control laws. The strange system somehow survived the war, working well enough during the era of lifetime employment. But the American economy changed. Lifetime employment disappeared, first evolving into a wink and a nod fiction amid periodic layoffs, then a historic anachronism. Americans commonly change jobs every few years, switching insurance (and doctors) for each new employer. The Affordable Care Act promised to change all this, and for a few years it did. Millions of American entrepreneurs, freelancers, early retirees, and gig workers used the ACA to buy health insurance without becoming beholden to an employer. But skyrocketing costs have now made “Affordable Care Act” plans unaffordable for middle class workers. In Washington DC, the cheapest plans for 2027 for 55 and older workers — the most expensive age bracket — now cost around $15,000 per person per year. For this author, premiums have gone up 226% since 2016.1
Who you blame for rising costs depends on where you stand in America's partisan divide. Democrats blame Republicans for refusing to renew government subsidies. Republicans blame Democrats for running an unsustainable entitlement program on the backs of American taxpayers. Both arguments have merit. Clearly, the end to subsidies for middle class Americans that resulted from the 2015 government shutdown had a huge impact on premiums — it nearly doubled the cost for Americans in the most expensive 55+ bracket. If a couple's household income is over $81,760, they now get no government subsidy and must pay the full cost levied by the insurance company.2 While Republicans are clearly to blame for this, it's hard to argue with their logic that taxpayers should not subsidize healthcare premiums for the middle class. And it is Democrats who deserve much of the blame for those high premiums. Since the days of Hillary Clinton's failed Health Security Act in 1993, Democrats have been obsessed with pushing for "comprehensive" coverage. This means that health care plans should cover everything, no matter how expensive, regardless of whether the insured wants the particular coverage or not. Since the beginning, all plans offered under the Affordable Care Act must cover maternity care even for single men and enrollees over 55. Over the years, mandated inclusions have expanded, especially in Democratic controlled jurisdictions, driving costs higher. In Washington DC, a one party state that will soon coronate a Democratic Socialist mayor, the city passed a 2018 law requiring all ACA plans to provide mental health care at the same level as physical ailments. This is not just for serious mental illnesses like schizophrenia or suicide risk — it covers extremely common behavioral and social like substance abuse and marriage counseling.3 Another law taking effect in 2026 mandated zero co-payments for HIV treatments.4 Being generous may be a virtue, but not when you demand others pay the bill. In Washington DC, the government fines anybody who refuses to buy expensive plans with these generous mandated coverages. Middle class households that buy cheaper medical insurance not meeting DC's generous mandates get hit with a yearly $2,385 "Shared Responsibility" tax.5 But given the skyrocketing costs of ACA plans, it will soon make sense for residents of Washington DC to opt-out of the ACA and just pay the fine. The only alternative is to take a full time job offering health insurance or move someplace with lower insurance costs. This is exactly the kind of conundrum that the ACA was supposed to prevent. To be clear, price increases in DC are not representative of all sates -- some states are working to slow price increases, but premiums are still rising everywhere. Given America's polarized political climate, there is little hope for a fix for these increases any time soon. Many of the original ideas of the ACA started with free market Republicans like former Senator Mitt Romney (partnering with private insurers, creating health exchanges, etc) but became politically radioactive in the Republican Party after the ACA became associated with their nemesis President Obama, leading President Trump to promise to repeal "Obamacare." While Republican attempts at repeal never succeeded, Democrats' “generosity” is quietly helping accomplish the same end. Say goodbye to the brief era of health care freedom that the ACA gave to Americans. It was nice while it lasted. Notes: 1. Monthly premiums paid by author for Care First Blue Cross Blue Shield Bronze PPO Plan 2018: $765.54, 2021: $1068.81, 2024: $ $1190.58, 2025: $2163.90, less $353.5 PTC = $1810.40, 2026: $2163.90, 2027: $2,493.67 2. Kaiser Family Foundation, Congressional District Interactive Map: How Much Will ACA Premium Payments Rise if Enhanced Subsidies Expire? February 5, 2026 3. DC City Council, D.C. Law 22-242. Behavioral Health Parity Act of 2018, as posted Oct. 27, 2026 4. DC City Council, B26-0159 - PrEP DC Act of 2025, March 20, 2026 5. DC Office of Tax and Revenue, 2025 Schedule HCR, as posted Oct. 27, 2026 |
 SITE
INDEX |
|
 |
Home |
|
|
Archives |
|
Identity
Theft |
|
Social
Security |
|
Canadian
Drugs |
|
Iraq |
|
|
|
Search |
|
Travel Pages |
|
Central
Asia |
|
Guatemala |
|
India |
|
Peru |
|
|
|
Personal |
|
Summer Calendar |
|
Feedback |
 |